GDP Dynamics Q3 Nowcast Holds at 2.46% as Treasury Yields Push Above 5%
Date: 2026-09-15Author: GDP Dynamics
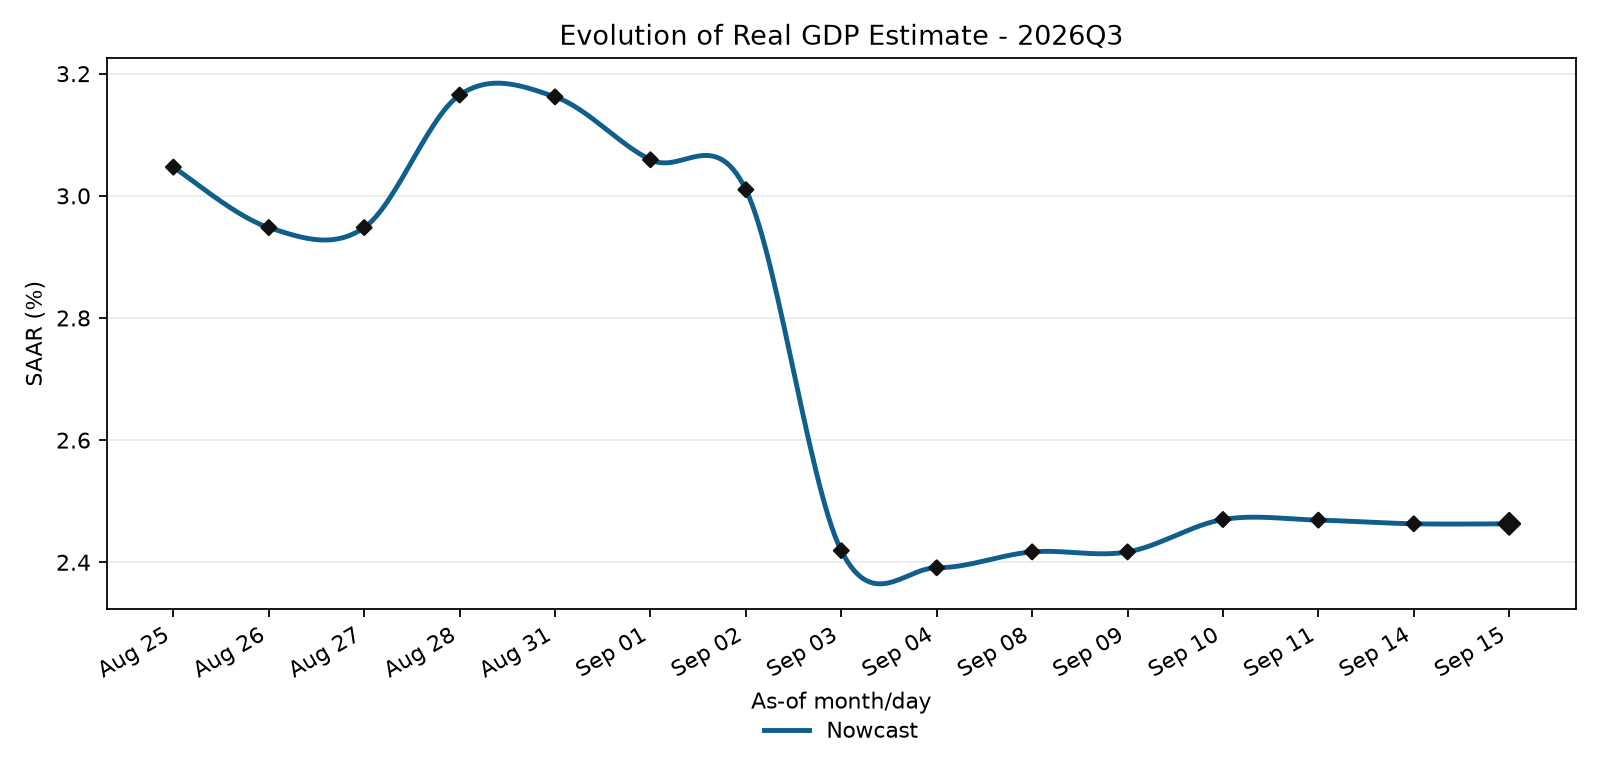
The GDP Dynamics nowcast for third-quarter U.S. real GDP growth held at 2.46% SAAR on September 15, unchanged from the previous update. That translates to roughly 0.62% quarter-over-quarter growth.
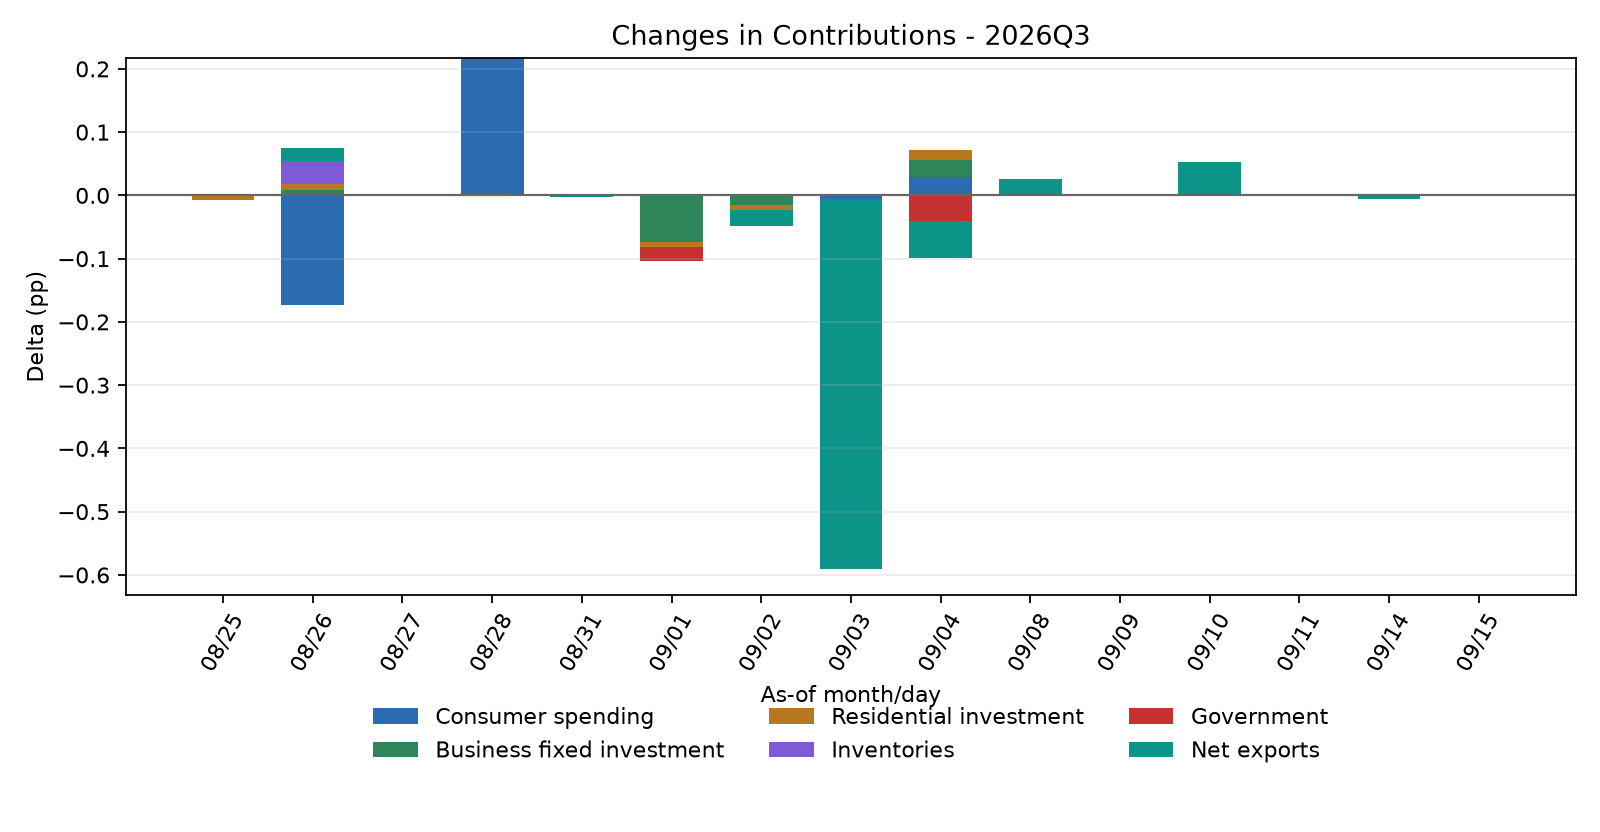
There was no meaningful change in the model's component contributions today. Instead, the latest available data point was the 10-year Treasury yield, which moved sharply higher as financial markets continued to reprice the outlook for inflation and monetary policy.
Nowcast Path
Treasury Yields Push Above 5%
The 10-year Treasury yield climbed above 5% and reached roughly 5.04% on September 15, its highest level since 2007.
The move came alongside another rise in oil prices and growing expectations that the Federal Reserve will raise its policy rate at its September meeting. Brent crude traded above $105 per barrel as renewed tensions in the Middle East kept pressure on energy markets.
That combination matters because higher energy prices can feed into inflation while higher Treasury yields tighten financial conditions throughout the economy. Mortgage rates, corporate borrowing costs and other longer-term interest rates are all influenced by movements in Treasury yields.
For the GDP Dynamics model, however, today's change in the 10-year yield was not enough to materially alter the Q3 growth estimate.
Where the Q3 Nowcast Stands
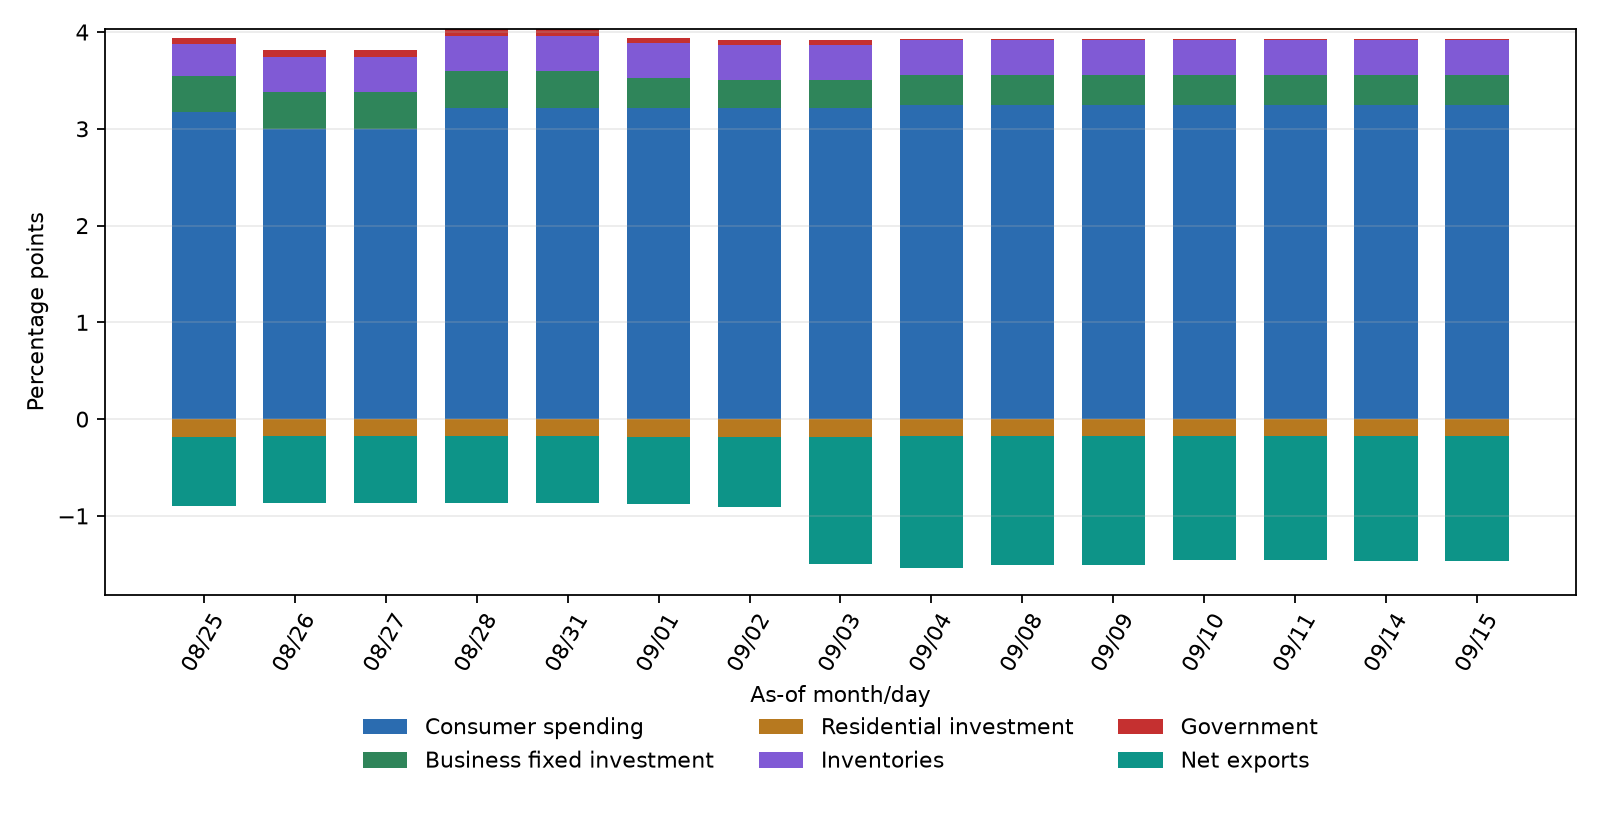
Consumer spending currently contributes 3.24 percentage points to the Q3 growth estimate. Net exports subtract 1.29 percentage points, partially offsetting that strength.
Contribution LevelsContribution Changes
Inventories add another 0.36 percentage points, while business fixed investment contributes 0.32 percentage points. Residential investment subtracts 0.17 percentage points, and government spending currently adds approximately 0.01 percentage points.
These are contribution levels rather than changes from yesterday's estimate. None of these components moved enough in today's update to change the headline nowcast.
That distinction is important. Consumer spending has the largest positive contribution because it is structurally the largest component of GDP, but today's update does not provide evidence of a new acceleration in consumption.
The Bigger Question Is Financial Conditions
Although today's data left the Q3 nowcast unchanged, the bond-market move is worth watching.
A 10-year Treasury yield around 5% represents considerably tighter long-term borrowing conditions. If those rates persist, the effects can eventually show up in housing, business investment and interest-sensitive consumer spending.
That does not necessarily mean those components weaken immediately. The nowcast is designed to respond as the underlying economic data arrive rather than mechanically translate every financial-market move into GDP growth.
For now, the incoming information remains consistent with real GDP growth of approximately 2.46% SAAR in Q3 2026. Today's update is therefore less about a change in the current-quarter estimate and more about a potential source of pressure to watch as additional September data arrive.